Unlicensed HMO bridging finance: how to fund an HMO before it's licensed
If you're buying or refinancing an HMO that isn't licensed yet, you'll quickly find that the usual HMO mortgage lenders won't help. This guide explains why, how investors use bridging finance to get through the unlicensed stage, and what to check before you commit.
On this page
The problem with unlicensed HMOs
You generally can't get a standard HMO mortgage on an unlicensed or non-compliant HMO. HMO mortgage lenders normally want to see a valid licence, or at least a completed licence application, on a property that's compliant and let. Until you're there, the property is usually unmortgageable.
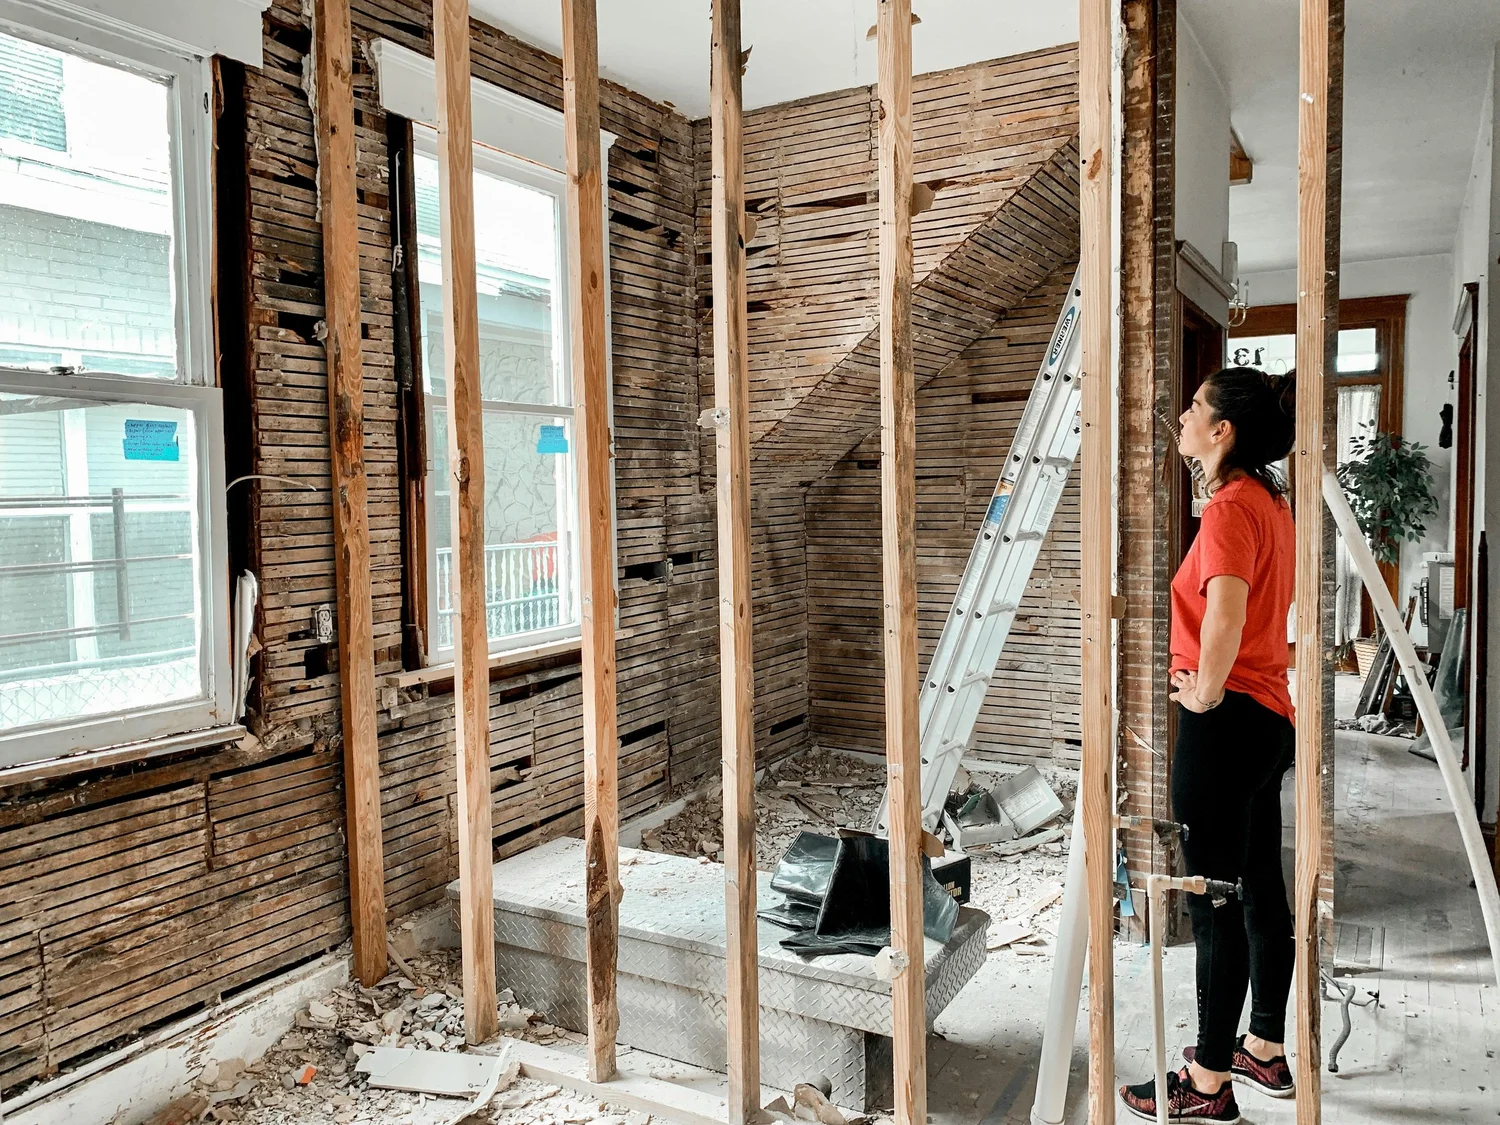
That's a problem, because unlicensed property is often where the opportunity is. A single let that would work better as an HMO, a tired HMO that needs fire safety works before the council will license it, a property bought at auction with no paperwork in place. In each case you need money to buy it and get it compliant, but the long-term lender only arrives once you've done the work.
Bridging finance is how most investors close that gap. It lends on the property as it is today, without a licence, and is repaid by an HMO mortgage once the licence is in place. Our HMO bridging loans page covers the product itself in full: rates, terms and case studies. This guide focuses on the unlicensed stage specifically.
What counts as an unlicensed HMO?
For finance purposes, an unlicensed HMO is a property that is, or is going to be, a house in multiple occupation but doesn't yet have the licence it needs. An HMO is a home shared by three or more people who form two or more households.
In practice we see a handful of situations. Some investors are buying a standard single let to convert. Others are part-way through a conversion, with layout or fire safety works still under way. Some have already applied for a licence and are waiting on the council. And some are buying an existing HMO that has been run without the right licence and needs bringing up to standard.
A licence is normally only needed once the property is actually occupied as an HMO above the council's threshold. So it's perfectly legal to buy or refinance a property you intend to run as an HMO before it's licensed. The difficulty is purely the finance.
Why bridging finance fits the unlicensed stage
A bridging loan doesn't need a licence at completion. The lender is interested in the property's value today, your plan for it and how you'll repay. Interest is usually rolled up or retained, so there's nothing to pay each month while the property isn't earning, and works can be funded in stages as they're done.
That covers everything an HMO mortgage can't. You can buy or refinance quickly, in as little as 5 to 10 working days on a straightforward case, carry out the works, deal with the licence and any planning, and let the rooms. Once the property is compliant and income-producing, the HMO mortgage repays the bridge.
How a typical project runs
Most unlicensed HMO projects follow the same broad shape.
Bridge on the day-one value
The lender values the property as it stands, usually as a single let or vacant house, and lends against that. No licence is needed to complete.
Carry out the works
Fire doors and alarms, layout changes, kitchens and bathrooms, room sizes. Works money can be released in stages.
Get the licence, and planning if needed
Apply once the property meets the council's standards. In an Article 4 area or for a large HMO, planning comes first.
Refinance or sell
Move onto a specialist HMO buy-to-let mortgage once licensed and let, or sell, and repay the bridge.
The full purchase, convert and refinance cycle, including how staged works funding and lending against the value after works operate, is set out on the HMO bridging loans page. If you're converting a single let from scratch, our guide to funding an HMO conversion goes into more detail.
How lenders value an unlicensed HMO
This catches people out. On day one, the lender values the property on its current residential use and condition, compared with similar houses nearby. It doesn't value it as a running HMO, and it doesn't count the rent you plan to earn.
That's deliberately conservative, and it's what makes lenders comfortable lending before the licence is in place. Where the works are clearly defined, some lenders will also look at the value after works, which can increase what you can borrow. Depending on the property and the loan size, the valuation might be a full inspection, a desktop report or, on simpler cases, no physical valuation at all.
The value that really matters for your profit comes later, when the HMO mortgage lender values the finished, licensed property. Some value HMOs like ordinary houses, others on the rent. It's worth knowing which approach your likely refinance lender takes before you buy.
Licensing, planning and Article 4: what to check first
Before you buy, be clear on three things: which licence applies, whether you need planning, and whether the area has an Article 4 Direction. Between them they decide whether the property can run as an HMO at all, and how long it'll take to get there.
Licensing. Mandatory licensing applies to HMOs with five or more people from two or more households, across England. Many councils also run additional licensing for smaller HMOs, and some run selective licensing for all rented homes in certain areas. Requirements and timescales vary a lot between councils, sometimes between neighbouring ones.
Planning. Turning a house into a small HMO for up to six people is permitted development in most of England, so no planning is needed. A large HMO of seven or more people is a sui generis use and almost always needs full planning.
Article 4. Many councils, particularly in university cities and town centres, have removed the permitted development right with an Article 4 Direction. There, even a small HMO conversion needs planning. If you're buying an existing HMO in an Article 4 area, make sure the HMO use is lawful, through a planning permission or a certificate of lawful use, because both your bridging lender and your eventual mortgage lender will check.
Fire safety, minimum room sizes and amenity standards all need to meet the council's rules, and conversion works often need building control sign-off too. Take proper planning and licensing advice before you commit. Our HMO licensing summary shows how each position affects a bridge.
Getting the term right
Most unlicensed HMO bridges run for 3 to 18 months. The mistake we see most often is choosing a term based on how long the works will take, and forgetting everything that comes after.
Work it out backwards instead. Start with when you'd realistically be able to refinance, which is after the works, after the licence comes through, after the rooms are let, and after any tenancy history your mortgage lender wants. Then add a buffer. Council licensing can take weeks in one area and months in the next. If you think the refinance will be ready in eight months, ask for twelve. Extending a bridge later costs more than building the time in at the start.
Where unlicensed HMO projects go wrong
The risks are well understood, and most can be handled with the right structure from day one.
Licence delays are the most common. Council backlogs can add months, so the answer is a term that reflects your council's actual timescale rather than the best case.
Works overruns come next. A properly costed schedule of works, a contingency and staged drawdowns that track progress all help keep the project on budget.
Planning surprises, especially Article 4, can stop an HMO plan entirely. Confirming the planning position and lawful use before you buy removes most of that risk.
Refinance delays happen when the exit hasn't been tested. Lending on today's residential value rather than future rent, and checking the refinance before completion, keeps you out of trouble if things take longer.
Getting out of the bridge
For most investors, the exit is a specialist HMO buy-to-let mortgage once the property is licensed, compliant and let. Lenders will want to see that route is realistic from the start, ideally with expected rents, a stress test and indicative terms from a mortgage broker.
The alternatives are selling once the property is licensed and let, when it's usually worth more as a running HMO, bringing it into a wider portfolio facility, or refinancing onto an ordinary buy-to-let mortgage if you decide to run it with fewer occupants so that no licence is needed.
Whichever route you choose, it's what the bridging lender will scrutinise most closely. More on exits, and three worked case studies, are on our HMO bridging loans page.
Looking at an unlicensed HMO?
See rates, terms and how we structure HMO bridges, or send us the deal for a same-day decision in principle.
Unlicensed HMO bridging FAQs
Can I get a mortgage on an unlicensed HMO?
Usually not. Specialist HMO mortgages normally need a valid licence, or at least a completed application, on a compliant, let property. Until then most lenders will decline, which is why investors use bridging finance first and refinance once the property is licensed.
Can I get bridging on an unlicensed HMO?
Yes, it's one of the most common uses of HMO bridging. The lender values the property as it is today, typically lends up to 75% of that value, and looks closely at your route to compliance and your exit.
Do I need a licence before the bridge completes?
No. A licence isn't needed at completion, particularly if the property is empty, being converted or not yet operating as an HMO. You get the licence during the loan term, before you refinance.
How do I exit the bridge?
Usually by refinancing onto a specialist HMO buy-to-let mortgage once the property is licensed, compliant and let. Selling is the other common exit. Build enough time into the term for the works, the licence and any tenancy history the mortgage lender wants.
What if the property is in an Article 4 area?
You'll need full planning permission to convert a house into an HMO, even a small one. If you're buying an existing HMO, make sure the HMO use is lawful, with a planning permission or certificate of lawful use, because both the bridging lender and the refinance lender will check.
How is an unlicensed HMO valued?
On its day-one residential value, compared with similar houses, not on future HMO rent. Some lenders will also consider the value after works if the scope is clearly defined.
About the author
Harry Baker
Harry holds an MSc in Real Estate & Finance from the University of Reading. He arranges bridging for HMO investors buying, converting and refinancing across England, Scotland and Wales.
This guide is general information, not legal, planning or financial advice. Licensing and planning rules vary by council.
Your property may be repossessed if you do not keep up repayments on a loan secured on it. All finance is subject to underwriting, valuation and legal due diligence. Figures are indicative. Aura Capital is a trading name of Chammosair Limited, registered in England & Wales, company no. 15786496. Aura Capital is a broker, not a lender, and is not authorised or regulated by the Financial Conduct Authority. We do not arrange regulated loans or give financial advice.