HMO bridging loans to buy, convert and license before you refinance
An HMO mortgage needs the property licensed, compliant and let. If you're buying an unlicensed HMO, converting a single let or racing an auction deadline, you're not there yet. An HMO bridging loan funds the purchase and the works now, and is repaid by an HMO mortgage once the property is licensed and tenanted.
Rates from 0.55% a month, up to 85% LTV on qualifying cases, £26,000 to £10 million. Same-day decision in principle.
On this page
The short version
- HMO bridging funds an HMO before it qualifies for an HMO mortgage: unlicensed, mid-conversion, or bought at auction.
- The classic model: buy, convert, license, let, then refinance onto a specialist HMO buy-to-let mortgage.
- Rates from 0.55% a month. Most HMO cases price between 0.75% and 1.10%.
- Up to 85% LTV on qualifying cases, with 75% the most common. Works funded up to 100% in stages.
- Licensing and Article 4 are the first things a lender checks. Confirm both before you buy.
- Most HMO mortgage lenders want six months of tenancy before refinancing, so build that into your term.
What is an HMO bridging loan?
An HMO bridging loan is short-term finance secured on a house in multiple occupation, or a property being converted into one, before a standard HMO mortgage is available. Lenders focus on the property's value, your plan and your exit, not your income. It's repaid by refinancing onto an HMO mortgage, or by selling, once the property is licensed and let.
A standard HMO mortgage wants a finished product: licensed, compliant, let and producing rent. It also takes 8 to 12 weeks. That rules it out for most of the ways investors actually make money from HMOs, such as buying unlicensed stock, converting single lets or buying at auction.
A bridge covers the gap between where the property is today and when it's ready for a mortgage. Interest is usually rolled up or retained, so there's nothing to pay each month while there's no rent coming in.
Standard HMO mortgage
- Must be licensed and fully compliant
- Needs rental income running
- 8 to 12 weeks, too slow for auctions
- Won't fund conversions or unlicensed property
- Income and credit come first
HMO bridging loan
- Licensed and unlicensed HMOs accepted
- Funds conversion works in stages
- No monthly payments with rolled or retained interest
- Completes in days, in time for auctions
- The property and exit come first
How HMO conversion bridging works: buy, convert, refinance
Most HMO bridges follow the same cycle. Get each stage right and the refinance at the end takes care of itself.
Buy
A day-one advance funds the purchase, typically up to 75% LTV and up to 85% on qualifying cases. Confirm licensing and Article 4 before you exchange.
Convert
Works are released in stages as each milestone is evidenced, with some lenders funding up to 100% of the costs in arrears. On qualifying conversions, lenders can lend against the value after works (GDV) rather than today's value.
License
Apply for the HMO licence once the property meets the council's standards. Council timescales vary from weeks to months, so check yours early.
Let
Fill the rooms. Most HMO mortgage lenders want six months of tenancy history before they'll refinance.
Refinance
Move onto a specialist HMO buy-to-let mortgage at the new value, repay the bridge and, on a good project, pull out some of your capital.
Add up works, licensing, letting and six months of tenancy, then add a buffer. If you think the refinance will take 8 months, ask for 12. Extensions carry extra fees, so building the buffer in on day one is much cheaper.
Some HMO mortgage lenders value on a bricks-and-mortar basis, comparing with ordinary houses nearby. Others use an investment basis based on the rent, which is usually higher for a good HMO. Which one your refinance lender uses can make a big difference to how much capital you get back, so check before you commit to the project.
HMO bridging loan rates and terms in 2026
Rates start from 0.55% a month on straightforward licensed HMOs at a conservative LTV with a strong exit. Most HMO cases price between 0.75% and 1.10% a month, depending on LTV, licensing, the works and how clear the exit is.
| Scenario | Indicative rate | Typical LTV | Notes |
|---|---|---|---|
| Licensed HMO, clean case, strong exit | 0.55% to 0.75% pm | Up to 75% | Confirmed refinance, rental evidence, experienced borrower |
| Licensed HMO purchase, standard | 0.75% to 0.90% pm | Up to 75% | Where most licensed HMO purchases price |
| Unlicensed HMO, compliance works needed | 0.85% to 1.05% pm | Up to 70% | Needs a clear route to compliance and some experience |
| Single let to HMO conversion | 0.90% to 1.10% pm | Up to 75% or GDV | Detailed works schedule and exit plan. GDV lending available |
| Adverse credit | 0.95% to 1.40% pm | Up to 70% | The property and exit carry most weight |
What moves your rate
- LTV. The biggest factor. 60% to 65% gets the best pricing, and 80% and above costs noticeably more.
- Licensed or not. A licensed HMO is lower risk. Compliance works after completion cost more.
- Works. Cosmetic updates and full structural conversions are priced differently.
- Exit. A rental estimate and a BTL stress test from a mortgage broker beat a vague plan to refinance.
- Experience. Established HMO investors get sharper pricing than first-timers.
- Valuation route. AVM and desktop valuations often get better terms than a full inspection.
| Term | Typical range | Notes |
|---|---|---|
| LTV | Up to 85% | 75% is where most cases complete. GDV lending on qualifying conversions |
| Loan size | £26,000 to £10m | Larger facilities on stronger cases and portfolios |
| Term | 3 to 24 months | Allow for works, licensing and six months of tenancy |
| Interest | Retained, rolled or serviced | Rolled or retained means no monthly payments while there's no rent |
| Works | Up to 100%, in stages | Released in arrears against an approved schedule |
| Arrangement fee | From 1%, typically 1.5% to 2% | Taken on completion. Check whether it's on the gross or net loan |
| Borrower | Individual, company or SPV | New companies accepted, with director guarantees |
| Broker fee | None upfront | We're paid by the lender on completion, disclosed before you proceed |
Add up interest, the arrangement fee, valuation, legal costs on both sides and any exit fee. A 1% exit fee on a £300,000 loan adds £3,000 when you repay. We model the whole cost before recommending a lender.
Model your HMO project
Pick your scenario and enter the price and works. For a fuller breakdown, use our HMO bridging calculator.
When is HMO bridging used?
Whenever the property isn't ready for an HMO mortgage yet, because of licensing, works, planning, timing or tenancy.
Licensed HMO purchase or refinance
Buy or refinance a running HMO quickly, for portfolio growth, equity release or an auction deadline. Usually the best-priced scenario.
Unlicensed HMO
Buy now, do the compliance works, get the licence, then refinance. Lenders look at the route to compliance, the timescale and the exit.
Single let to HMO conversion
Fund the purchase and the conversion: layout changes, fire safety and extra rooms. Refinance once it's let.
Auction purchases
HMO mortgages can't meet a 28-day deadline. Get a DIP before you bid. See auction bridging.
GDV lending on conversions
On qualifying projects, lenders lend against the value after works, which cuts the cash you need on day one.
Portfolio equity release
Raise money quickly from licensed HMOs you own to fund the next purchase, then refinance back onto term debt.
HMO licensing: what lenders check
Licensing is one of the first things a lender asks about. A clear, realistic route to a licence speeds up approval and improves the LTV and rate you get.
| Licence | When it applies | Effect on your bridge |
|---|---|---|
| Mandatory | 5 or more tenants from more than one household sharing facilities. Every council in England | Most lenders are comfortable if there's a realistic route to the licence. Allow for the council's processing time |
| Additional | Smaller HMOs, typically 3 or 4 tenants, where the council has a scheme. Varies by council | Confirm at enquiry. It can differ from one street to the next, and some lenders want the licence near-certain |
| Selective | All privately rented homes in designated areas, HMO or not | Lower risk with an established route. Still budget the cost and time |
| Unlicensed | Operating as an HMO without the licence it needs. Common on conversion and value-add deals | Case by case: the route to compliance, timescale, your experience, the exit and the works |
Neighbouring councils can have completely different licensing rules and timescales. Wrong assumptions about whether a licence is needed, or how long it takes, are among the most common reasons HMO bridges overrun. Check with your council before you buy.
Planning and Article 4 Directions
Confirm the planning position before you approach a lender. Lenders aren't put off by planning. They're put off by uncertainty about it.
Small HMO (C3 to C4), most areas
Converting a house into a small HMO for up to 6 people is permitted development in most of England. No planning needed.
No planning neededArticle 4 areas
Many university cities and town centres remove that right with an Article 4 Direction. Even a small C4 conversion then needs full planning.
Planning neededLarge HMO (7 or more people)
Sui generis use. Almost always needs full planning, Article 4 or not. Lenders want it granted or a credible application underway.
Always planningHow Article 4 affects your bridge
- Converting in an Article 4 area: you'll need planning first, or a lender willing to fund while it's pending, usually at a lower LTV.
- Buying an existing HMO in an Article 4 area: the lender will want proof the HMO use is lawful, such as a planning permission or a certificate of lawful use. Without it, the value and the exit are at risk.
- Check before you buy: the council's website lists its Article 4 Directions. Tell us the position at enquiry and we'll pick lenders who are comfortable with it.
Works funding and staged drawdowns
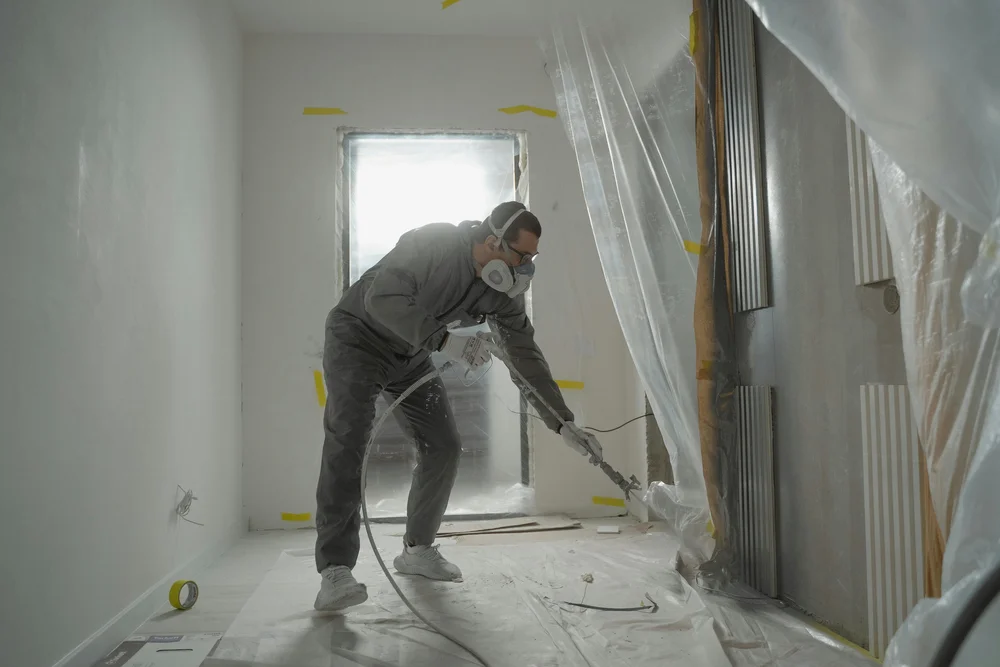
Works money isn't paid on day one. The day-one advance covers the purchase or refinance, and the works are released in stages as you show progress. Some lenders fund up to 100% of the works in arrears on an approved schedule.
What lenders need before drawdowns
- A costed schedule of works
- Contractor details and track record
- A works timeline with milestones
- Progress evidence: photos, receipts or surveyor sign-off
- A clear route to licensed, let and refinanceable
Lending against the value after works
On qualifying conversions, some lenders size the loan on the gross development value rather than today's value. That raises what you can borrow and cuts the equity you need. It works best with comparable lettings, rental evidence, a clear scope and an experienced contractor. Total debt is then capped against that end value, so a strong uplift gives you more room.
More detail in our guide to funding an HMO conversion with bridging finance and on refurbishment bridging loans.
The HMO investor checklist: what to confirm before you buy
Most HMO bridges that go wrong do so because of something that could have been checked before exchange.
Planning and licensing
- Article 4 status for the street
- Which licensing scheme applies, and the council's timescale
- For an existing HMO, proof the use is lawful
- Whether 7 or more occupants means sui generis planning
The building and the numbers
- Room sizes against the national licensing minimums
- Fire safety: fire doors, alarms and escape routes
- Kitchen and bathroom ratios the council requires
- Rents from comparable HMOs nearby
- How your refinance lender values HMOs
How to apply for an HMO bridging loan
The fastest cases arrive with the licensing, planning, works and exit already clear. Preparation does more for speed than anything else.
Feasibility and DIP
We look at the property, licensing, planning, works and exit, and confirm a realistic LTV, rate and valuation route before you pay anything.
Valuation and legals together
AVM the same day, desktop in 1 to 2 days, or a full RICS inspection in 3 to 5 days on larger or complex conversions. Solicitors instructed at the same time.
Formal offer
You'll need ID, the legal pack, the costed works schedule and evidence of your exit, such as a rental estimate and BTL stress test. We handle the lender's questions.
Completion and drawdown schedule
Funds released on completion, with the works schedule agreed from day one. We plan the refinance from the day you complete.
Send these for a same-day DIP
- Address and current condition
- Licensed, unlicensed or conversion
- Planning: permitted development or Article 4
- Loan, LTV and term
- Works scope and budget
Also helpful
- Your exit, with evidence
- Borrower: individual, company or SPV
- Solicitor details, as early instruction saves days
Exit strategies for HMO bridging loans
The exit is the most closely checked part of an HMO application. It decides whether you're approved and how the loan is priced.
Refinance to an HMO mortgage
The most common exit, once the property is licensed, compliant and let. Get indicative mortgage terms from a broker, and allow for six months of tenancy.
Sale
For value-add and resell strategies. Bring comparables and agent feedback, and allow time, as HMOs have a smaller pool of buyers than ordinary houses.
Development exit
For larger conversions, a development exit bridge gives time to license, let and stabilise the income before the long-term refinance.
HMO bridging case studies
Single let to 6-bed HMO, Leeds
A below-market single let bought for £195,000 and converted with layout and fire safety works costing £38,000. £146,250 at 75% LTV and 0.89% pm over 11 months, with works in three stages. Licensed, let at £2,400 a month and refinanced at a £320,000 valuation onto a £240,000 HMO mortgage. Net equity created after all costs: £68,500.
£146,250, 75% LTV, 0.89% pmUnlicensed HMO at auction, Birmingham
An unlicensed HMO in an Article 4 area with a 28-day deadline, already declined by two mainstream lenders. Planning was confirmed compliant before submission, the solicitor was instructed before the auction and a desktop valuation came back on day 2. It completed on day 22, with licensing now underway.
£124,600, 70% LTV, day 22 of 28Equity release on a licensed HMO, Manchester
An experienced investor needed capital for a new purchase. £273,600 at 72% LTV and 0.79% pm on a £380,000 licensed HMO repaid the £88,600 mortgage and released £185,000 in 8 working days. The exit is a refinance back onto an HMO mortgage at month 6, with no exit fee.
£185,000 released, 8 working daysWho can get an HMO bridging loan?
Lenders care most about the property, the plan and the exit, not your income or employment.
Borrower
Aged 18 and over, with most lenders up to 85. UK residents and non-UK nationals with specialist lenders. Individuals, companies, LLPs, SPVs and trusts. First-time HMO investors and experienced developers.
Property
England, Scotland or Wales. Licensed, unlicensed or conversion. 3 to 10+ bedrooms. Freehold or leasehold. Minimum value usually £75,000. The planning position must be clear or clarifiable.
Exit
Credible and achievable within the term. For a refinance, the rent must pass an HMO mortgage stress test. For a sale, comparables and realistic pricing.
Bad credit
It doesn't rule you out. Satisfied CCJs, defaults, past arrears and discharged bankruptcy are regularly considered where the property and exit are strong, usually with a higher rate and a lower LTV. See bad credit bridging loans.
Limited companies and SPVs
Widely available, and new companies are accepted. Directors usually give personal guarantees, so their credit is considered too. Tell us the full picture early.
HMO bridging loan FAQs
What is an HMO bridging loan?
Short-term finance secured on a house in multiple occupation, or a property being converted into one, before an HMO mortgage is available. Lenders focus on the property, your plan and the exit rather than your income. It's used for purchases, conversions, unlicensed HMOs and auctions, and repaid by an HMO mortgage or a sale.
How does HMO conversion bridging work?
A day-one advance funds the purchase, then the works are released in stages as each milestone is completed, up to 100% of the costs on an approved schedule. Once the property is licensed and has around six months of tenancy, you refinance onto a specialist HMO mortgage and repay the bridge.
What LTV can I get on an HMO bridging loan?
Up to 85% on qualifying cases, though most complete at around 75%. Unlicensed HMOs and adverse credit cases are usually up to 70%. On qualifying conversions, some lenders lend against the value after works, which increases what you can borrow.
Can I get bridging on an unlicensed HMO?
Yes, it's one of the most common HMO bridging cases. Lenders look at the route to compliance, the timescale, your experience and the exit. Expect up to 70% LTV at 0.85% to 1.05% a month.
How does Article 4 affect HMO bridging?
An Article 4 Direction removes the right to convert a house into a small HMO without planning. In those areas you need full planning for the conversion, and if you're buying an existing HMO the lender will want proof the use is lawful. Without that, fewer lenders will help and the LTV is usually lower. Always check before you buy.
What exit strategies work for HMO bridging?
Most often a refinance onto a specialist HMO mortgage once the property is licensed, compliant and let, with around six months of tenancy. Selling also works with good comparables. On larger conversions, a development exit bridge can give extra time to stabilise the income first.
How long do HMO bridging loans take?
Clean cases on an AVM or desktop valuation with a solicitor ready are fastest. AVMs come back the same day, desktops in 1 to 2 days and full inspections in 3 to 5 days. For auctions, instruct the lender and solicitor the day the hammer falls, or before.
What are typical rates for HMO bridging?
From 0.55% a month on clean licensed HMOs at a conservative LTV. Most cases price between 0.75% and 1.10% a month. Conversions run 0.90% to 1.10%, and adverse credit 0.95% to 1.40%. Compare the total cost, not just the rate.
Do I need planning permission for an HMO conversion?
Not usually for a small HMO of up to 6 people, which is permitted development in most of England. You do in an Article 4 area, and almost always for a large HMO of 7 or more people.
Can the works be funded within the bridge?
Yes. Works are released in stages as you show progress, and some lenders fund up to 100% in arrears on an approved schedule. You'll need a costed schedule, contractor details and a timeline.
Can I get HMO bridging with bad credit?
Often, yes. Satisfied CCJs, defaults, arrears and discharged bankruptcy are regularly considered where the property and exit are strong. Expect up to 70% LTV and rates from 0.95% a month.
Can I apply through a limited company?
Yes, through a company, LLP or SPV, including newly formed ones. Directors usually give personal guarantees.
Who wrote this page
Harry Baker
Harry holds an MSc in Real Estate & Finance from the University of Reading. He arranges HMO purchase, conversion and refinance bridging for investors across England, Scotland and Wales.
- Team transacted
- £500m+
- Lender panel
- 50+
How we compiled the figures
Rates, LTVs and terms reflect HMO cases placed through our lender panel and are reviewed monthly. Licensing and planning rules vary by council. Always confirm the position with yours.
Related bridging products
Each product page has its own criteria and rates.
Fund your HMO from purchase to refinance
Send the address, licensed or unlicensed status, the works, the loan, the term and your exit. We'll confirm the same day whether it works, the realistic LTV and rate, and the quickest route to completion. No upfront fees.
Your property may be repossessed if you do not keep up repayments on a loan secured on it. All finance is subject to underwriting, valuation and legal due diligence. Licensing and planning rules vary by council and this page is general guidance. Figures are indicative, based on our lender panel in October 2026. Aura Capital is a trading name of Chammosair Limited, registered in England & Wales, company no. 15786496. Aura Capital is a broker, not a lender, and is not authorised or regulated by the Financial Conduct Authority. We do not arrange regulated loans or give financial advice.