Bridging loans and development finance, built around your deal.
We arrange finance for property purchases, refinancing, refurbishment and development across the UK. You deal with one specialist who reads your case properly, takes it to the lenders that fit and sees it through to completion.
- From 0.53%a month on qualifying bridging
- £26,000 to £10,000,000+larger facilities considered
- 50+ lendersspecialist bridging and development
- 3 to 18 monthstypical bridging terms
No credit search to get a quoteA lender may run one later, and we'll tell you first.
No upfront feesEvery cost is set out in writing before you commit.
One specialist throughoutFrom first call to funds at your solicitor.
Problems solved, deals completed.
A few cases we have arranged, and how each one was structured.
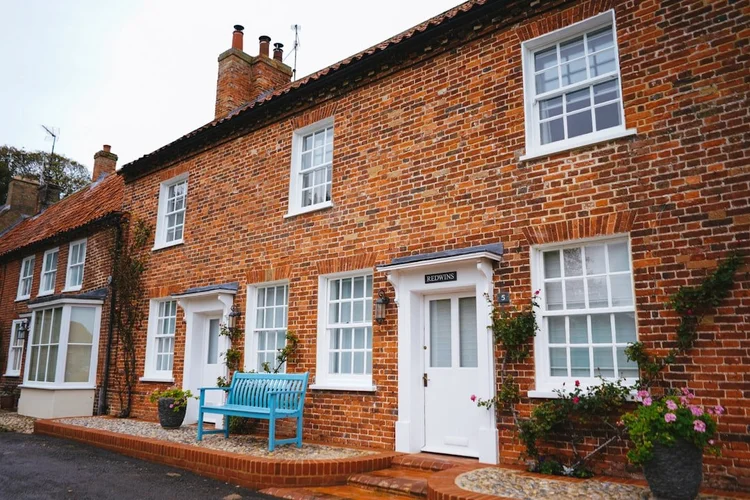 Fully approved in 42 minutes
Tenanted auction purchase, lease in dispute
- Problem
- Another lender declined at application over the lease
- Facility
- £65,250 at 75% LTV, desktop valuation
- Timescale
- Fully approved in 42 minutes, completed on the deadline
- Outcome
- Purchase completed with the tenant in place
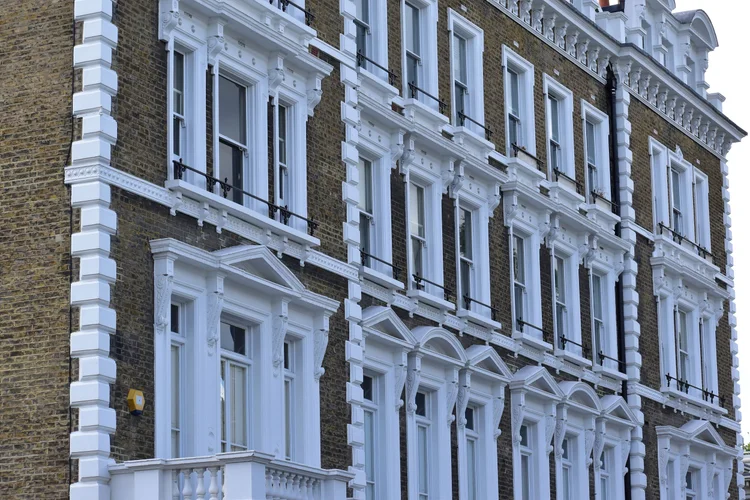 14 days
Two prime addresses, receivers instructed
- Problem
- Lender in enforcement, sale at risk, adverse credit
- Facility
- £3,266,874 at 66.7% LTV, 0.85% a month
- Timescale
- 14 days from instruction to drawdown
- Outcome
- Receivers stood down, orderly sale preserved
 £3,900,000 GDV
21-unit commercial-to-residential conversion
- Problem
- Funding needed to finish the scheme
- Facility
- £325,000 at 35% LTV
- Timescale
- No valuation or build warranty needed at drawdown
- Outcome
- Works funded through to completion
Finance for each stage of a property deal.
Bridging loans
Short-term finance to buy, refinance or release capital, repaid by a sale or refinance.
Get a full quote →Refurbishment finance
The purchase and the works, funded on day one or in stages, then refinanced at the new value.
Refurbishment finance →Development and conversions
Conversions and permitted development schemes, with funds drawn as the work progresses.
Development finance →Auction finance
Finance arranged around your contractual completion deadline, ideally agreed before you bid.
Auction finance →Development exit
Refinance a completed scheme to repay the build loan and allow time to sell or let the units.
Development exit →Adverse credit
Adverse credit considered case by case, with the property and exit carrying most weight.
Bad credit bridging →Experience where deals usually get stuck.
We lead with the difficult part
Leases, title issues, adverse credit or a tight deadline go to the lender first, so a decline happens before you spend money, not after.
See the Preston case →We move when it's urgent
Where time is short, we focus on the lenders and valuation routes that can actually meet the date.
See the London refinance →We match the lender to the scheme
Development, conversion and refurbishment lenders differ widely. We place each case with lenders that suit the asset and the plan.
See the Manchester scheme →From first call to funds, in three steps.
- Day one
Tell us the deal
Use the bridging calculator or call us. We'll ask about the property, the amount, the timescale and the exit.
- Usually within a day
We find the lender
We discuss the case with suitable lenders and come back with terms and every cost in writing.
- Often one to three weeks
Funds at your solicitor
We progress the valuation and legal work with the lender and your solicitor through to completion.
What is a bridging loan?
Short-term finance secured on property, usually for 3 to 18 months. It's used to buy, refinance or renovate quickly, and is repaid by selling the property or refinancing onto a longer-term loan.
How quickly can you arrange funding?
Many bridging loans complete in one to three weeks. Desktop or automated valuation routes can be quicker. Development finance usually takes longer because of the extra due diligence.
Can I borrow with adverse credit?
Adverse credit is considered case by case. Many specialist lenders look at CCJs, defaults and missed payments, though they may affect the rate or how much you can borrow.
What does it cost?
Bridging rates start from 0.53% a month on qualifying cases. Lenders usually charge an arrangement fee, and there are valuation and legal costs. There are no upfront fees, and every cost is confirmed in writing before you commit.
How much can I borrow?
Loans start from £26,000, typically up to 70% to 75% of the property value for standard bridging, with higher leverage on some refurbishment purchases. Larger facilities, including £10m and above, are considered individually.
Prefer to talk it through?
Call, WhatsApp or email. You'll speak to someone who arranges bridging and development finance every day.
Discuss your deal.
Send us the figures or call. We'll tell you how lenders are likely to view it and what it will cost.
Your property may be repossessed if you do not keep up repayments on a loan secured on it. Bridging finance is short-term borrowing and needs a clear exit. All figures are indicative and subject to lender underwriting, valuation and legal due diligence. Aura Capital is a trading name of Chammosair Limited, registered in England & Wales, company no. 15786496. Aura Capital is not authorised or regulated by the Financial Conduct Authority.